
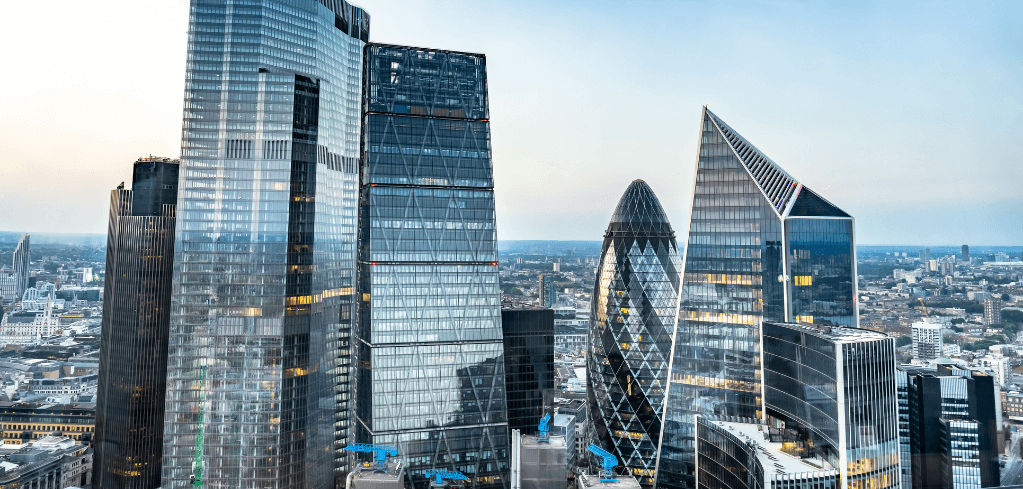
London Office Market | Q3 2026
Explore the key trends shaping London's office market in Q3 2026, including rental growth, supply constraints, occupier demand, development pipeline activity and the increasing appeal of locations such as Canary Wharf and the City Fringe.
Report summary
The Q3 2026 report highlights a London office market where demand for high-quality Grade A workspace continues to significantly exceed supply, underpinning rental growth across the capital's core business districts.
While economic and political uncertainty remains, occupier activity from financial services, legal, technology and AI businesses continues to support a resilient market. With development pipelines constrained and substantial volumes of future supply already pre-let, occupiers are increasingly broadening their search to more affordable submarkets.
At a glance
Demand remains strongest amongst financial services, legal, technology and AI occupiers, with AI businesses alone leasing more than 500,000 sq ft during the first half of 2026.
Canary Wharf recorded London's strongest rental growth over the last 12 months (+9.1%), reflecting improving occupier sentiment, Elizabeth Line connectivity and significant cost advantages compared with core Central London locations.
The City of London continues to experience acute Grade A supply shortages, driving headline rents above £100 psf for prime space and over £150 psf on upper floors of landmark buildings.
Development pipelines remain constrained, with only 39% of the 26.1 million sq ft pipeline currently under construction and meaningful new supply unlikely to ease market pressures before 2027.
Prime rents continue to rise across the City and West End, with Mayfair and St James's remaining London's most expensive office market at approximately £264 psf total occupancy cost.
Pre-letting activity continues to increase, reducing future tenant choice and encouraging occupiers to engage with the market earlier to secure suitable accommodation.
Owner-occupation is becoming a more prominent strategy, with businesses increasingly evaluating acquisition opportunities alongside traditional leasing options.
Download the latest London Office Market report
Discover the latest insights into London's office market and what they mean for landlords, occupiers and investors.
Commentary
The London office market remains firmly landlord-favourable, driven by a persistent imbalance between demand and supply for best-in-class Grade A office space. Occupiers continue to prioritise buildings with strong sustainability credentials, premium amenities and high-quality workplace environments, resulting in robust demand for newer stock while older space faces growing competitive pressures.
Development pipeline
Higher construction costs, elevated financing rates and extensive pre-letting activity continue to limit the availability of future office supply. Although the development pipeline totals approximately 26.1 million sq ft, a significant proportion remains at planning stage, while much of the space under construction is already committed. As a result, occupiers are facing declining choice and longer planning horizons.
Canary Wharf
Canary Wharf's resurgence continues to gather momentum. Strong transport links, improved placemaking, a growing residential and leisure offering, and significantly lower occupancy costs than the City or West End are attracting businesses seeking high-quality office space at better value. Recent major lettings, including Deutsche Bank's 151,000 sq ft commitment, demonstrate growing confidence in the location.
Sustainability
Environmental performance remains a key driver of occupier decision-making. Buildings with strong EPC ratings and modern sustainability credentials continue to command rental premiums and attract the strongest demand. Conversely, older buildings with weaker environmental performance are facing increasing obsolescence and pressure to undergo refurbishment or repositioning.
Occupiers
For occupiers, securing high-quality space is becoming increasingly challenging. Early engagement with the market, flexibility around location and consideration of pre-let opportunities will be essential. Locations including Canary Wharf, Farringdon, Shoreditch, Battersea and Hammersmith are expected to benefit from businesses seeking a balance between quality, connectivity and cost efficiency over the coming year.
The Tenant Representation Team
- Loading...
- Loading...
- Loading...
- Loading...
- Loading...
Download the latest London Office Market report
Discover the latest insights into London's office market and what they mean for landlords, occupiers and investors.