Two Adjoining Farms in North Yorkshire
North Yorkshire
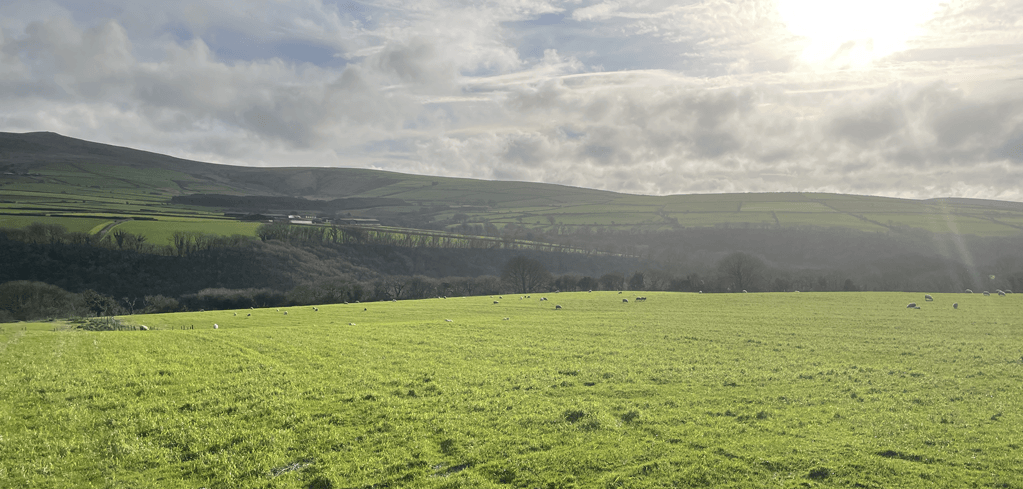
The property is two adjoining farms comprising the following a traditional farmhouse occupied by a partner in the farm business, a cottage occupied by a partner in the farm business, two ranges of traditional and modern farm buildings, Modern broiler unit let to a third party and 350 acres of farmland.
The property had a combined Market Value of circa £7,000,000. The farmland and modern general purpose agricultural buildings continue to qualify for 100% Agricultural Property Relief (APR). The land is actively farmed and the ownership and occupation tests are met, meaning these assets should be fully relieved from IHT. The combined value is £3,500,000.
The traditional buildings include an element of non-agricultural value of circa £100,000, which exceeds their agricultural value and therefore does not qualify for APR. The buildings are owned personally by a partner in the farm business, with the partnership occupying the land. The land therefore qualifies for BPR at a reduced rate of 50%.
Both the farmhouse and cottage, valued at £1 million together, are occupied by working farmers. The APR on the dwellings is limited to the agricultural value, which is defined by the IHT act as the value the agricultural property would have if it were subject to a perpetual covenant prohibiting its use otherwise than as agricultural property. The cottage is subject to an agricultural occupancy condition and therefore the market value is considered to be equal to the agricultural value, whereas with the farmhouse the agricultural value is limited to 70% of the market value.
The position of the poultry unit is unclear. The definition of agricultural property refers to any buildings used in connection with the intensive rearing of livestock or fish, if the building is occupied with agricultural land or pasture and the occupation is ancillary to that of the agricultural land or pasture. Given the poultry unit is a standalone entity and therefore it cannot be argued that it is both occupied with agricultural land and is ancillary to that of the agricultural land, it is considered that the poultry unit would not qualify for APR. As the poultry unit is let it would not qualify for Business Property Relief (BPR) as a standalone entity, had the building been operated in hand it is considered that it would qualify for 100% BPR.
When the poultry unit is considered as part of the wider estate/business, they may still attract 100% BPR if they form part of a predominantly trading business rather than an investment business. The farm operates traditional arable and sheep enterprises which generate relatively modest turnover and profit when considered against the poultry unit and therefore it is considered that there is currently limited scope to qualify for BPR on this basis.
This demonstrates the necessity to ensure that the correct business and ownership structures are put in place prior to establishing the new enterprises. The poultry unit was only built in the last 10 years and had professional advice been sought at the outset the potential IHT liability could have been mitigated.
Asset / Issue | Value | APR Position | BPR Position | Key Commentary / Considerations |
|---|---|---|---|---|
Farmland (350 acres) | £3,500,000 | Qualifies for 100% APR on the agricultural value. | Not required. | Mainly relieved from IHT with active farming evidenced. |
Core agricultural buildings | Included in £3,500,000 | Qualify for 100% APR, with the exception of the non-agricultural value that qualifies for 50% BPR. | 50% relief on the non- agricultural value element. | Potential to obtain full relief on the non-agricultural value element if the potential development land becomes a partnership asset. |
Farmhouse & Cottage | £1,000,000 | Likely to qualify for APR, albeit limited to the agricultural value. | Not relevant if APR applies. | Maintain evidence of occupation and involvement in the farm business. |
Let Poultry Unit | £2,500,000 | Does not qualify for APR. | Possible 100% BPR, albeit this would require the overall business to be wholly or mainly trading rather than an investment business. | Consider the main activities of the business, its assets, sources of income over a reasonable period. |
- Farms, Estates & Rural Leisure
- Valuations
Date
September 2026