
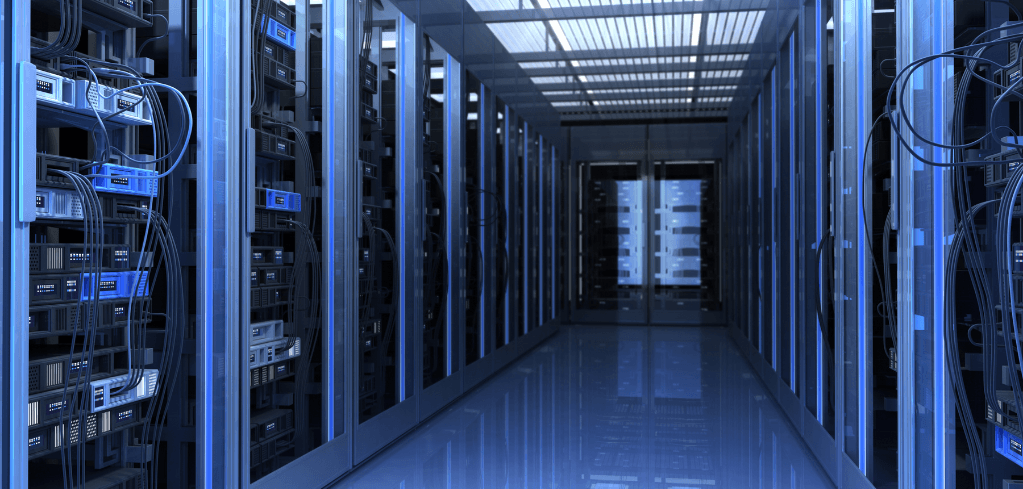
Data Centres Without the Drama
Hyperscale AI campuses dominate the debate, but most facilities are being delivered with few planning constraints.
Overview
John Mason, Associate at Carter Jonas discusses data centre solutions, delivering expert property advice.
The image of a data centre has become one of a vast AI campus: acres of buildings, thousands of servers, huge power requirements and difficult questions about grid capacity, water and local impact. However, these “Hyperscale Data Centres” are only one piece of the jigsaw; they and their complications are far from representative of the whole market.
My recent work with nLighten has been at the other end of the spectrum. nLighten operates Edge Data Centres, smaller facilities that bring computing and storage capacity closer to users. Across the UK nLighten’s network extends to Birmingham, Bristol, Chester, Leeds, Liverpool, London, Milton Keynes, Nottingham, Rugby and Swindon and there are more than 30 locations elsewhere in Europe.
Edge facilities are intended to reduce latency by shortening the distance data has to travel. For businesses using real-time applications, cloud services, AI inference, 5G or the Internet of Things, milliseconds can matter, which creates a need for distributed infrastructure close to centres of economic activity rather than one or two very large national sites.
The physical form can be surprisingly ordinary. Several of the facilities I have worked on occupy established industrial or employment sites and look much more like conventional warehouse buildings than the popular image of a futuristic AI campus. Some data centres have been operating since the 1980s or 1990s without neighbouring communities necessarily being aware of them.
John Mason
Associate, Planning & Development
MRTPI

Data centres have been hiding in plain sight
Yet the debate is becoming distorted by scale. The Government’s Estimate of Data Centre Capacity: Great Britain 2024 believed there to be around 1.6GW of colocation data centre IT capacity two years ago, of which 1.048GW was in London. An Edge facility can be modest by comparison. nLighten’s Chester site, for example, provides 2,040 sq m of colocation space with an end-state capacity of 6MW.
The planning work is correspondingly different. On behalf of nLighten, we have been dealing with operational enhancements such as new chillers and generators, internal reconfiguration, fencing, façade openings and car-park alterations, alongside newer and more efficient plants. Since Carter Jonas was appointed in January 2025, permissions have been secured for works in Bristol, Milton Keynes, Birmingham, Chester, Liverpool and Hoddesdon, with Nottingham also progressing.
In my experience these applications have attracted little neighbour opposition and have not needed to be heard at planning committee. While data centres are not necessarily impact-free, controversy is not inevitable: a well-sited facility on land allocated for employment can be a relatively conventional planning proposition.
Why industrial land should remain the first choice
Perhaps the most important question is whether the next generation of data centre demand can be accommodated on existing industrial and employment land.
There is much to recommend that approach: the principle of development is already established; road access exists; buildings may be capable of adaptation and there is often some existing utility infrastructure. Re-use can also avoid the landscape and land-use issues that accompany major greenfield development.
But ageing industrial estates are not necessarily data centre-ready. Power supply is usually the first test and it can still be decisive. A site needs appropriate fibre connectivity, enough room for plant such as chillers, generators and substations, and a relationship with neighbouring uses that can accommodate operational noise and servicing. Data centres are also classed as “essential infrastructure” in flood risk terms, so more vulnerable than other industrial and employment uses.
Those constraints call for a comprehensive site appraisal rather than speculative assumptions that any redundant warehouse can simply be ‘flipped’. For landowners and investors, the valuable question is not whether a building looks suitable but whether the site has the combination of electricity, connectivity, cooling, space and planning status that makes the use deliverable.
When data centres become infrastructure projects
The Government’s UK Compute Roadmap forecasts that the UK will require at least 6GW of AI-capable data centre capacity by 2030, around three times the capacity available today. Hyperscale data centres are an essential part of the solution, but at the larger end of the market, both the numbers and the planning questions become very different. Carter Jonas has advised Microsoft on a hyperscale data centre of about 34,500 sq m in Newport and is advising UKAEA at Culham, where the proposed catalyst for the Government’s first AI Growth Zone is a 37,000 sq m data centre using a dedicated 400kV supply.
As scale increases, the planning exercise becomes less about accommodating a building on a site and more about understanding the infrastructure system needed to support it. Electricity demand may require new substations or wider network reinforcement. Cooling and water requirements can become more significant. Construction traffic, landscape effects, resilience and the relationship with other major infrastructure all warrant greater scrutiny. In some cases, the enabling infrastructure may be as important to deliverability as the data centre itself.
This is also where the consenting route can change. Most data centres will continue to be determined through the conventional Town and Country Planning Act process, but Government policy (the policy paper Delivering AI Growth Zones) recognises some very large schemes may be sufficiently significant to be determined by the Nationally Significant Infrastructure Project regime. A forthcoming National Policy Statement for data centres is intended to give greater clarity.
Those projects therefore fall within the skill set of our Consents team, which advises on larger and more strategically significant schemes, including Development Consent Orders and the infrastructure required to support them.
The planning process must judge the development, not the technology
Regardless of size, however, it is the controversy which currently surrounds AI that poses a problem. Notwithstanding dystopian prophecies of superhuman intelligence bringing an end to the human race, there is concern about the energy demands of data centres: the International Energy Agency estimates that electricity generation supplying data centres worldwide will rise from about 460TWh in 2024 to more than 1,000TWh by 2030.
In the UK, data centres were designated as Critical National Infrastructure in 2024, reflecting their importance to the economy and public services and demand continues to grow. Planning therefore has to reconcile the need for this infrastructure with its local and environmental effects. That means power demand, water use where relevant, flood risk, noise, visual impact, resilience and the supporting infrastructure a scheme requires.
Increasingly, however, objections to data centre planning applications can become entangled with wider anxieties about AI itself: employment, energy consumption, water use or the social consequences of the technology. Those are legitimate public debates, but they are not always questions that a local planning application can answer.
For planners, developers and local authorities, the focus should be the development in front of them. What is its scale? Where is it located? What infrastructure does it require? What are its measurable impacts and how can they be mitigated?
Carter Jonas’ experience of Edge facilities is much less dramatic than the headlines might imply. Data centre growth does not have to mean vast greenfield campuses generating local hosepipe bans. The challenge for planners is not to treat every data centre as a hyperscale AI campus, but to recognise that the sector spans everything from modest employment-site upgrades to nationally significant infrastructure. Understanding that distinction will be essential if the UK is to deliver the digital infrastructure its economy increasingly depends upon.
Research and insights
 Read insight
The UK has Industrial and Infrastructure strategies
Explore how the UK's Industrial and Infrastructure strategies shape economic growth. Carter Jonas provides expert insights on policy impacts and investment opportunities.
 Read insight
Planning in three dimensions
Discover expert 3D planning insights from Carter Jonas. Explore innovative strategies and solutions for effective three-dimensional planning to transform your projects.
 Read insight
A Future for Historic Buildings
Discover how Carter Jonas helps secure a future for historic buildings with expert heritage property advice, preservation strategies, and specialist real estate solutions.
Tailored newsletters for you
Sign up to our newsletter to receive further information and news tailored to you.